Safe temporary protection
Discuss active water entry and exposed layers promptly. Keep records of the protection and contact the insurer about requirements. Access and conditions need to be safe.
Understand the roof work and the insurer’s decision, including protection, deductibles and the conditions of your own policy.
A roof inspection and an insurance claim answer different questions. The roofer assesses the roof condition and work; the insurer applies the policy to coverage and payment.
If you are considering a claim, start with what changed at the property and preserve useful observations safely. We help explain the roofing concern and proposed work while you discuss the policy process with your insurer.
Keep the roof condition, policy decision and authorized project connected without treating them as one approval.
A free inspection can establish accessible damage and practical protection or repair options. Tell us when the change was noticed and whether water is entering.
Ask about notice, required evidence and deadlines under the actual policy. Keep safe photographs and records of observed damage and temporary protection.
Connect the proposed repair or replacement parts to the observations. Clarify any difference in scope or payment before deciding to authorize work.
The policy and claim handling determine how these terms apply. Ask the insurer to explain the figures in your own estimate.
| Term | What it means in the discussion |
|---|---|
| Deductible | The portion of a covered claim assigned to you under the policy. It is separate from the roof work scope. |
| Actual cash value | A payment basis that can account for depreciation under the policy. It is not necessarily the full replacement price. |
| Replacement cost | A policy payment basis tied to replacing covered property, with its conditions, limits and timing. |
| Depreciation | An amount the insurer assigns under the claim terms. Whether it can be recovered and what is required depends on the policy. |
| Scope difference | A roofing recommendation and an insurer estimate can include different items. Resolve the reason for that difference rather than assume automatic payment. |
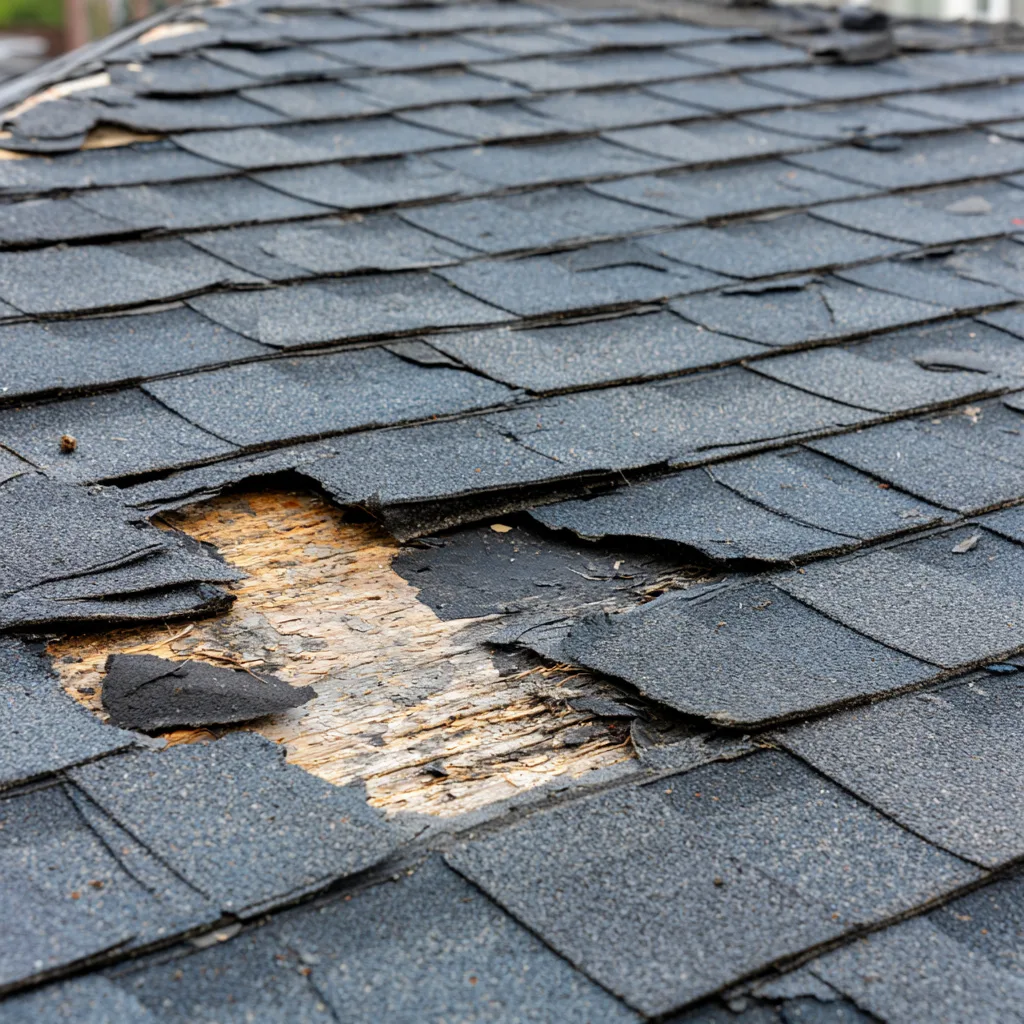
The roofing discussion should make the repair boundary clear. Missing shingles may need a defined replacement section; damaged flashing or supporting layers may change that section. Broader deterioration needs its own explanation rather than being attributed to a storm by date alone.
Useful observations connect location, condition and the proposed work. They can help you understand a roofing estimate and ask the insurer about an item that differs in its claim estimate. A contractor’s recommendation still does not decide policy coverage.
For the physical damage assessment, see storm and hail roofing. The work should be selected from the roof condition and a clear agreement.
The damaged part, its location and any unresolved concealed condition.
The repair or replacement and its sound boundary.
The insurer’s coverage, deductible and payment conditions.
An exposed roof can need protection while the permanent scope and claim are still being discussed.
Discuss active water entry and exposed layers promptly. Keep records of the protection and contact the insurer about requirements. Access and conditions need to be safe.
Settle the repair or replacement scope, cost and agreement before proceeding. Temporary protection does not establish which permanent items are covered by the policy.
No. The inspection assesses the roof. The insurer decides coverage and payment under the policy and claim facts.
The assessment needs to distinguish actual damage, ordinary wear and other conditions. Extent, remaining material and policy terms matter; a mark alone does not establish a full-roof claim.
Ask the insurer for the deadlines and conditions that apply to your policy and claim. A deadline from general storm advice should not be assumed to apply to every roof.
The Arkansas Insurance Department Consumer Services provides consumer assistance. Keep the policy, correspondence and claim information available when seeking help.
Start with a free inspection of the property. We’ll help make the roofing decision clear while you discuss coverage with the insurer.